
Terafab Operating-Control Talks: A Field Guide to Who Builds, Who Runs and Who Owns the Yield
Ask any plant manager what happens when a vehicle or robotics company declares it will fabricate its own leading-edge logic, and the answer rarely starts with capital. It starts with three operational questions: who is allowed through the tool-room door, who signs off on process recipes, and who absorbs the cost when a ramp slips a quarter. The latest turn in the Terafab story puts those questions squarely in front of industrial readers, because reporting from DigiTimes indicates that Elon Musk is reworking how the Terafab chip plant program advances and that TSMC may be pulled back to the negotiating table, with control over wafer-fab construction and operation now the core issue rather than a side note.
The Positions on the Table, and How They Moved
Supply-chain information cited by DigiTimes suggests the conversation has shifted from a narrow arrangement — in which part of the campus would merely be leased to TSMC — toward a structure that grants the foundry a substantially larger role. Factory operating control, co-investment and technology cooperation are all described as items inside the discussion. TSMC may end up carrying primary responsibility for building and running the fab, while equity structure, investment ratios and the division of work remain unsettled. With AI chip demand pushing advanced packaging capacity into a tight state, packaging technology has also become a plausible bargaining chip.
What makes the episode useful for operations leaders is not the gossip around it but the sequence of stated positions, because each position corresponds to a different risk-transfer model:
- Early October: Musk confirmed that discussions with TSMC were under way.
- Shortly after: he stated that Tesla and SpaceX would build and operate Terafab themselves, with TSMC able at most to rent part of the facility.
- October 15: C.C. Wei, chairman and CEO of TSMC, told an earnings call that the company had sent a team to Texas to evaluate the site and had discussed capacity cooperation — while emphasizing that whenever TSMC participates in a wafer fab, operation must be handled by TSMC.
- Most recent reporting: the stance on cooperation has softened, and both sides are preparing to renegotiate.
Read as an engineering document, that timeline is a disagreement about accountability, not about money. Whoever operates the fab owns defect-density curves, tool-match decisions and qualification sequencing — three things that cannot be delegated by contract after the fact.
Three Governance Models, Compared on Shop-Floor Terms
The framework below is an illustrative comparison of standard arrangements, not a description of any term disclosed for Terafab. Its value is diagnostic: it shows what an industrial buyer gives up and buys back under each model.
| Model | Who runs the line | Owner’s capital exposure | Who carries yield accountability | Speed-to-volume realism |
|---|---|---|---|---|
| Space lease | Owner-operator team | Building plus most tooling | Owner’s process integration group | Slowest; every learning curve is paid for once in-house |
| Co-invested joint venture | Shared, defined by governance contract | Split by equity ratio | Negotiated, usually tracking the operator | Middle; needs a long dispute-resolution appendix |
| Operator-led build | Foundry partner | Partial capacity funding | Foundry partner | Fastest credible ramp, at the price of cost and mix control |
The Plan on Paper: Scale, Capital and Schedule
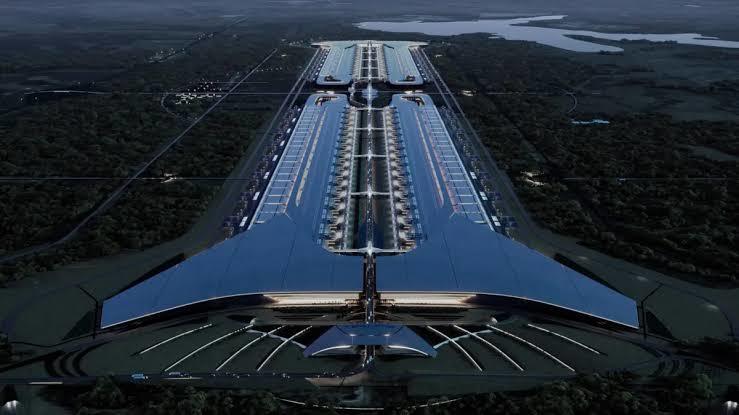
Terafab is being advanced jointly by SpaceX and Tesla, with the site set in Grimes County, Texas, in the United States. SpaceX’s published planning describes a campus that consolidates manufacture, packaging and test of advanced logic and memory chips in one place, with planned manufacturing space of more than 100 million square feet; first-phase spending by SpaceX and Tesla is expected at roughly $16.8 billion. SpaceX has said that future chip demand from Tesla and SpaceX is expected to exceed 1 terawatt of compute capacity, with Terafab output aimed at Tesla Optimus robots, Cybercab, and the space-based data centers SpaceX has outlined. The stated objective is to cut dependence on external chip capacity while expanding compute supply for AI and robotics work.
On execution, Tesla began constructing a research-type wafer fab in April this year at the north campus of its Texas Gigafactory, a facility treated as the pathfinder for Terafab. Musk has said the team plans to complete a first test chip in May or June 2027 and to reach scaled production in the third or fourth quarter of 2028 — while acknowledging that the schedule is “very aggressive” and that the project faces procurement challenges for advanced lithography and other semiconductor manufacturing equipment. Intel has also announced participation in Terafab, though the specific form of that cooperation has not been disclosed. If TSMC secures construction and operating leadership in a new round, the program’s cooperation architecture and the division of labor among participants would likely be re-cut.
A Six-Step Build-Readiness Sequence for Owner-Operator Projects
Independent of how the Terafab negotiation resolves, the same sequence applies to any industrial organization attempting leading-edge fabrication. Steps are ordered by the point of no return, not by organizational chart.
- Fix the operating model before fixing steel. Decide which of the three models above the site will run under, then write tool ownership, recipe ownership, PDK access and qualification sign-off into the same contract, not a later annex.
- Reserve long-lead capital equipment early. Industry analysis of lithography supply chains puts EUV order-to-delivery lead times in the range of 12 to 18 months for customers already in the queue, with standard EUV tools near $250 million and High-NA systems approaching $400 million each (CES Intelligence, EUV supply-chain risk analysis). A fab schedule that starts tool ordering after building design is complete is already behind.
- Size utilities in front-end engineering. Power, ultra-pure water, specialty gas and abatement must be contracted, not queued. Practitioner reviews of owner-side schedule risk consistently flag cleanroom fit-out as the underestimated item, with certification required before tool move-in (iRecruit, semiconductor fab construction cost and schedule analysis).
- Start the talent clock two years ahead of first wafer out. A joint employer survey by McKinsey & Company, the SEMI Foundation and the U.S. National Science Foundation projects a shortfall of as many as 157,000 skilled semiconductor workers in the United States by 2030, most acute in Texas, Arizona, California, New York and Ohio. This is a hiring-lead-time problem, not an HR problem.
- Treat packaging as inside the fence, not after it. Trade reporting through 2026 describes TSMC’s CoWoS advanced-packaging capacity as substantially sold out, while compiled industry forecasts show global CoWoS capacity moving from roughly 13,000–16,000 wafers per month in 2023 toward an estimated 90,000–110,000 in 2026 (SemiWiki industry capacity compilation). A wafer fab without secured packaging throughput delivers compute only halfway.
- Run a dual-track schedule. Keep an external foundry relationship live while the internal ramp is being built, so a two-quarter slip becomes a sourcing adjustment rather than a product launch cancellation.
Case Benchmark: What a Real Ramp Actually Took in the Desert
The most instructive comparable is not a challenger’s slide deck but the incumbent’s own transplant. TSMC’s Arizona site records that high-volume production on N4 process technology at the first fab started in the fourth quarter of 2024, with the second fab’s structure completed in 2025 (TSMC Arizona project page). Earlier, the company pushed the first plant’s opening from late 2024 into 2025 citing a shortage of specialized labor, and reported the second Arizona plant slipping toward 2027 or 2028 (Manufacturing Dive). That is the world’s most experienced operator relocating a process it already mastered, and it still needed years between groundbreaking, workforce build-out and volume.
Set against Terafab’s stated milestones, the comparison does not invalidate the plan; it sharpens what a project with a first test chip targeted for May or June 2027 and scaled output in the third or fourth quarter of 2028 must get right on day one: tool availability, an operator with a qualified process, and headcount hired before the building is finished rather than after.
Five Misconceptions That Distort Fab Decisions
- Confusing who pays with who operates. Capital contribution does not automatically confer process authority; yield is dictated by the team running the tools.
- Treating a fab as a construction project. The building is the cheap part; the schedule is set by qualification cycles, tool match and utility certification.
- Assuming wafer output equals compute supply. Without packaging and memory allocation, wafers do not convert into usable AI capacity.
- Assuming capital is the binding constraint. In the current U.S. market, skilled headcount and equipment lead times bind first.
- Reading renegotiation as reversal. A change in which terms are acceptable is not the same as a change in objectives — Musk’s stated goal of reducing external capacity dependence is unchanged in the reporting.
Checklist: Ten Questions Before Signing an Operating Agreement
- Is the operating party contractually accountable for yield and ramp timing, not only for equipment uptime?
- Who owns the recipe files, defect-inspection models and PDK, and can designs migrate to another site?
- Which tools are booked, at what slot dates, and what is the penalty for rescheduling?
- Which ISO 14644-1 cleanroom class applies to each area, and who certifies it before tool move-in?
- Are power, ultra-pure water and specialty gas volumes contracted, with a stated second-source plan?
- How many process engineers, equipment technicians and metrology staff are employed 24 months before first wafer out?
- Is advanced packaging co-located, or secured under a multi-year external agreement?
- What take-or-pay or minimum-volume exposure exists if the schedule moves by two quarters?
- Are spares, remote diagnostics and maintenance contracts transferable across sites and partners?
- Which forum arbitrates tool priority when two internal product lines — vehicle computing and robotics or space computing — both claim capacity?
Action Recommendations, by Role
- For executives at systems companies: model three ownership scenarios in parallel with three capital structures, and insist that the operating-rights variable is priced explicitly rather than buried in a partnership announcement.
- For production and operations leads: convert the schedule into an equipment-arrival and headcount-arrival plan. Every milestone from test chip to scaled production is a staffing event first.
- For procurement and supply-chain teams: obtain written lead-time commitments for capital tools and packaging slots now, and hold the second source rather than waiting for a decision.
- For plant and facility engineers: front-load utility sizing and cleanroom certification scope; treat fit-out as a schedule driver, not a finishing trade.
- For equipment and materials suppliers: an owner-operator program of this scale pulls upstream suppliers into one region. Qualify for multi-site, multi-partner support rather than a single-account relationship.
- For regional industrial policy observers and investors: watch equity structure, investment ratios and division of labor — those three unsettled items determine whether the campus is built as one operator’s line or several partners’ shared capacity.
Frequently Asked Questions
Is the Terafab project being cancelled?
No. The reporting describes a re-evaluation of the cooperation structure, not of the goal. Musk has continued to frame Terafab as a way to cut dependence on external chip capacity for Tesla and SpaceX, with output earmarked for Optimus robots, Cybercab and planned space data centers.
Why is operating control such a hard line for a foundry?
Because a process only performs as well as the team running it. Advanced logic fabrication couples lithography, etch, deposition and metrology in feedback loops measured in days; an operator without authority over recipes and tool sequencing cannot be held to a yield target. That is the substance behind C.C. Wei’s October 15 statement that TSMC participation requires TSMC operation.
What is the biggest schedule risk for a project of this type?
Not the building. Long-lead tooling and workforce. Order-to-delivery windows measured in quarters for advanced lithography, plus a U.S. labor gap projected at up to 157,000 skilled semiconductor workers by 2030, both bite before steel is topped out.
Should other manufacturers worry about a chipmaking project like this?
Indirectly, yes. When large end users internalize fabrication, regional competition for equipment service engineers, cleanroom trades and process talent intensifies for every local plant. Suppliers to automotive, robotics and data-center hardware should also track how packaging and memory allocation are secured, since those remain the shared chokepoints.
Where is the plan still blank?
Equity structure, investment ratios and the specific division of responsibilities. Intel’s participation has been announced without a disclosed cooperation mode, which means the eventual operating map may redraw more than two parties’ roles.
The practical takeaway for industrial readers is that the outcome of the Terafab talks will be legible long before any press release: in tool reservation lists, in utility interconnection contracts, and in how many qualified process engineers are walking the north campus of Tesla’s Texas Gigafactory two years before a target date of scaled production. Ambition announces itself; fabs are commissioned.
By Michael Torres, WorldIndustrialWeekly. Story tips and corrections: news@industrialweekly.com.