
WorldIndustrialWeekly Insight: Intel Q3 2026 Shows AI Demand, Memory Crunch, and Fab Halt Risks for Industrial Buyers
By Michael Torres | Industrial Weekly | WorldIndustrialWeekly
A supply pattern is forming for manufacturing, automation, and IT operations teams in which AI-related compute growth raises demand while memory cost pressure and a fabrication disruption at a site in Israel create timing gaps for buyers of Xeon-based server capacity, PC fleets, and enterprise computing hardware. The latest results from Intel provide a useful signal for plant, project, and procurement decisions because they connect macro technology investment with practical constraints: component availability, system prices, and replacement cycles.
Case view: Intel’s Q3 performance and the supply-side squeeze
For third-quarter 2026, Intel reported total revenue of $16.5 billion, up 21% year over year, while fourth-quarter guidance points to $15.0 billion to $16.0 billion and a non-GAAP gross margin of 38.0%, down from 44.1% in the third quarter.
The fourth-quarter outlook shows that the AI-related revenue surge does not erase near-term cost and supply problems. In Q3, server-side momentum was strong, but production constraints and memory price movement continued to shape both data center and client product availability.
What the numbers signal for operations and procurement
| Business line or market read | Reported fact | Operational implication |
|---|---|---|
| Data Center and AI group | Revenue was $7.3 billion, up 78% year over year, with strong demand from hyperscale, enterprise, and cloud customers. | Server refresh and AI infrastructure plans may remain active even when components are tight. |
| Xeon supply | Shortages of raw materials, substrates, and other critical components limited Intel’s ability to meet demand. | Purchase lead times and allocation risk matter more than list price alone. |
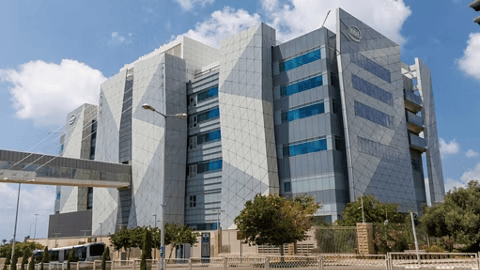
| Fab disruption | A two-week shutdown at an Intel fabrication facility in Haifa, Israel, following a gas explosion affected output. | Capacity recovery may arrive later than demand normalization. |
| Client Computing and Physical AI Group | Revenue declined 5% year over year to $8.1 billion. | PC-related budget planning faces weaker consumer hardware momentum. |
Fab interruption effects: wafer cycle time and write-offs
Because turning silicon wafers into finished chips takes roughly three months, output lost during a stoppage does not reappear quickly. Wafers still in process when the fab shut down are expected to be scrapped, and Intel CFO David Zinsner said on the earnings call that most write-offs should land in the fourth quarter, with no further scrapping expected in the first quarter. He said the fab disruption will have an estimated $300 million impact on revenue in the fourth quarter of 2026, with a similar impact in the first quarter of 2027.
Leadership statements: execution progress and unmet demand
Intel CEO Lip-Bu Tan linked the quarter to process and supply progress while acknowledging that customer demand exceeded available output.
“Our Q3 results demonstrate improving execution, meaningful progress expanding supply and continued advancement of our process technology,”
Tan said in the press release. During the earnings call, he added:
“I’m disappointed that we were not able to meet strong customer demand in this quarter,”
“We face near-term challenges, including manufacturing supply shortage, the unprecedented memory crunch, and the resulting softness in PC demand. But I remain confident in our path forward.”
Memory shortage and PC contraction: why system costs move in opposite directions
Memory suppliers have benefited from AI infrastructure investment. Samsung and SK Hynix reported record quarterly profits. At the same time, rising DRAM costs from vendors including Samsung, SK Hynix, and Micron forced PC makers to raise retail prices, prompting buyers to defer upgrades. That dynamic weighed on the Client Computing and Physical AI Group, where revenue declined 5% year over year to $8.1 billion.
“We expect the current environment to persist until memory availability and prices begin to normalize,”
“While the next few quarters will be challenging for the PC market, our roadmap continues to strengthen, and our long-term outlook remains positive.”
Tan described the path from constrained demand to normalization as a function of memory availability and pricing.
Counterpoint Research data: shipments, replacement cycles, and structural adjustment
Counterpoint Research data indicated that global personal computer shipments fell 21% year over year in the third quarter of 2026 to 57 million units. The firm forecasts a further 27% year-over-year decline in the fourth quarter.
Minsoo Kang, senior analyst at Counterpoint Research, framed the pressure as a consumer purchasing problem:
“The global PC market is facing mounting pressure as rising memory and component costs push system prices higher and force consumers to delay replacement purchases.”
David Naranjo, associate director at Counterpoint Research, described a longer cycle change:
“The PC industry is entering a period of structural adjustment, where rising component costs, higher system prices, and longer replacement cycles are fundamentally reshaping market dynamics.”
Capital planning: 2027 as an investment year
Intel’s CFO said the company does not expect positive free cash flow in 2027. Zinsner described 2027 as an “investment year,” while noting that the group plans to increase capital expenditure to rebuild production capacity.
Key misconceptions from this quarter’s data
- Growth in AI data center demand does not mean every hardware segment expands at the same rate. The quarter showed a structural divide: server and memory suppliers benefited, while consumer hardware faced cost pressure.
- A two-week fab halt is not only an operational accident. The wafer cycle, roughly three months, turns downtime into later write-offs and revenue impacts.
- Higher revenue in one quarter does not guarantee improved guidance in the next. The fourth-quarter range and lower margin expectation reflect cost and supply constraints.
- Record memory vendor profits and high DRAM prices are not neutral for buyers. They can raise system prices and defer PC upgrades.
Action advice for managers, engineers, and procurement teams
- Treat lead time, allocation, and substitution risk as core procurement metrics when planning Xeon capacity and AI server refreshes.
- Review PC replacement schedules with awareness that memory and component costs can push system prices higher and extend replacement cycles.
- Align capex and capacity assumptions with the company’s stated investment posture for 2027.
- Use the estimated $300 million impact, and the similar first quarter of 2027 effect, as a reminder that manufacturing disruptions can cross fiscal quarters.
FAQ: What the Q3 2026 results mean for industrial buyers
Why did Intel revenue rise while PC demand weakened?
Revenue rose to $16.5 billion, up 21% year over year, because AI-related data center demand offset constraints. At the same time, Client Computing and Physical AI Group revenue declined 5% year over year to $8.1 billion as memory costs raised PC prices and delayed upgrades.
What does the Haifa disruption mean for supply timing?
The shutdown lasted two-week after a gas explosion at an Intel fabrication facility in Haifa, Israel. Because chip making takes roughly three months, the effect could appear in later quarters. Intel expects an estimated $300 million revenue impact in the fourth quarter of 2026, with a similar impact in the first quarter of 2027.
Is the fourth quarter still an investment risk for capacity?
The quarter remains part of a broader capacity rebuild. Fourth-quarter guidance of $15.0 billion to $16.0 billion and 38.0% gross margin, down from 44.1%, shows pressure. The first quarter of 2027 and 2027 as an investment year show capacity work continues.
What related topics did the source connect to this reporting?
The source listed related Intel topics including Classiq, Tesla, SpaceX and Terafab.
WorldIndustrialWeekly, published by Industrial Weekly, summarizes these findings for industrial decision-makers; author Michael Torres, contact news@industrialweekly.com. The key signal is to separate growth narratives from supply realities. Intel’s Q3 shows AI demand, but component shortages, memory pricing, and a two-week fab halt still shape costs, availability, and replacement decisions across server, PC, and infrastructure purchasing.