
WorldIndustrialWeekly General: Intel Turns 18A and 14A Momentum into Foundry Proof Points as Lip-Bu Tan Explores AMD Cooperation
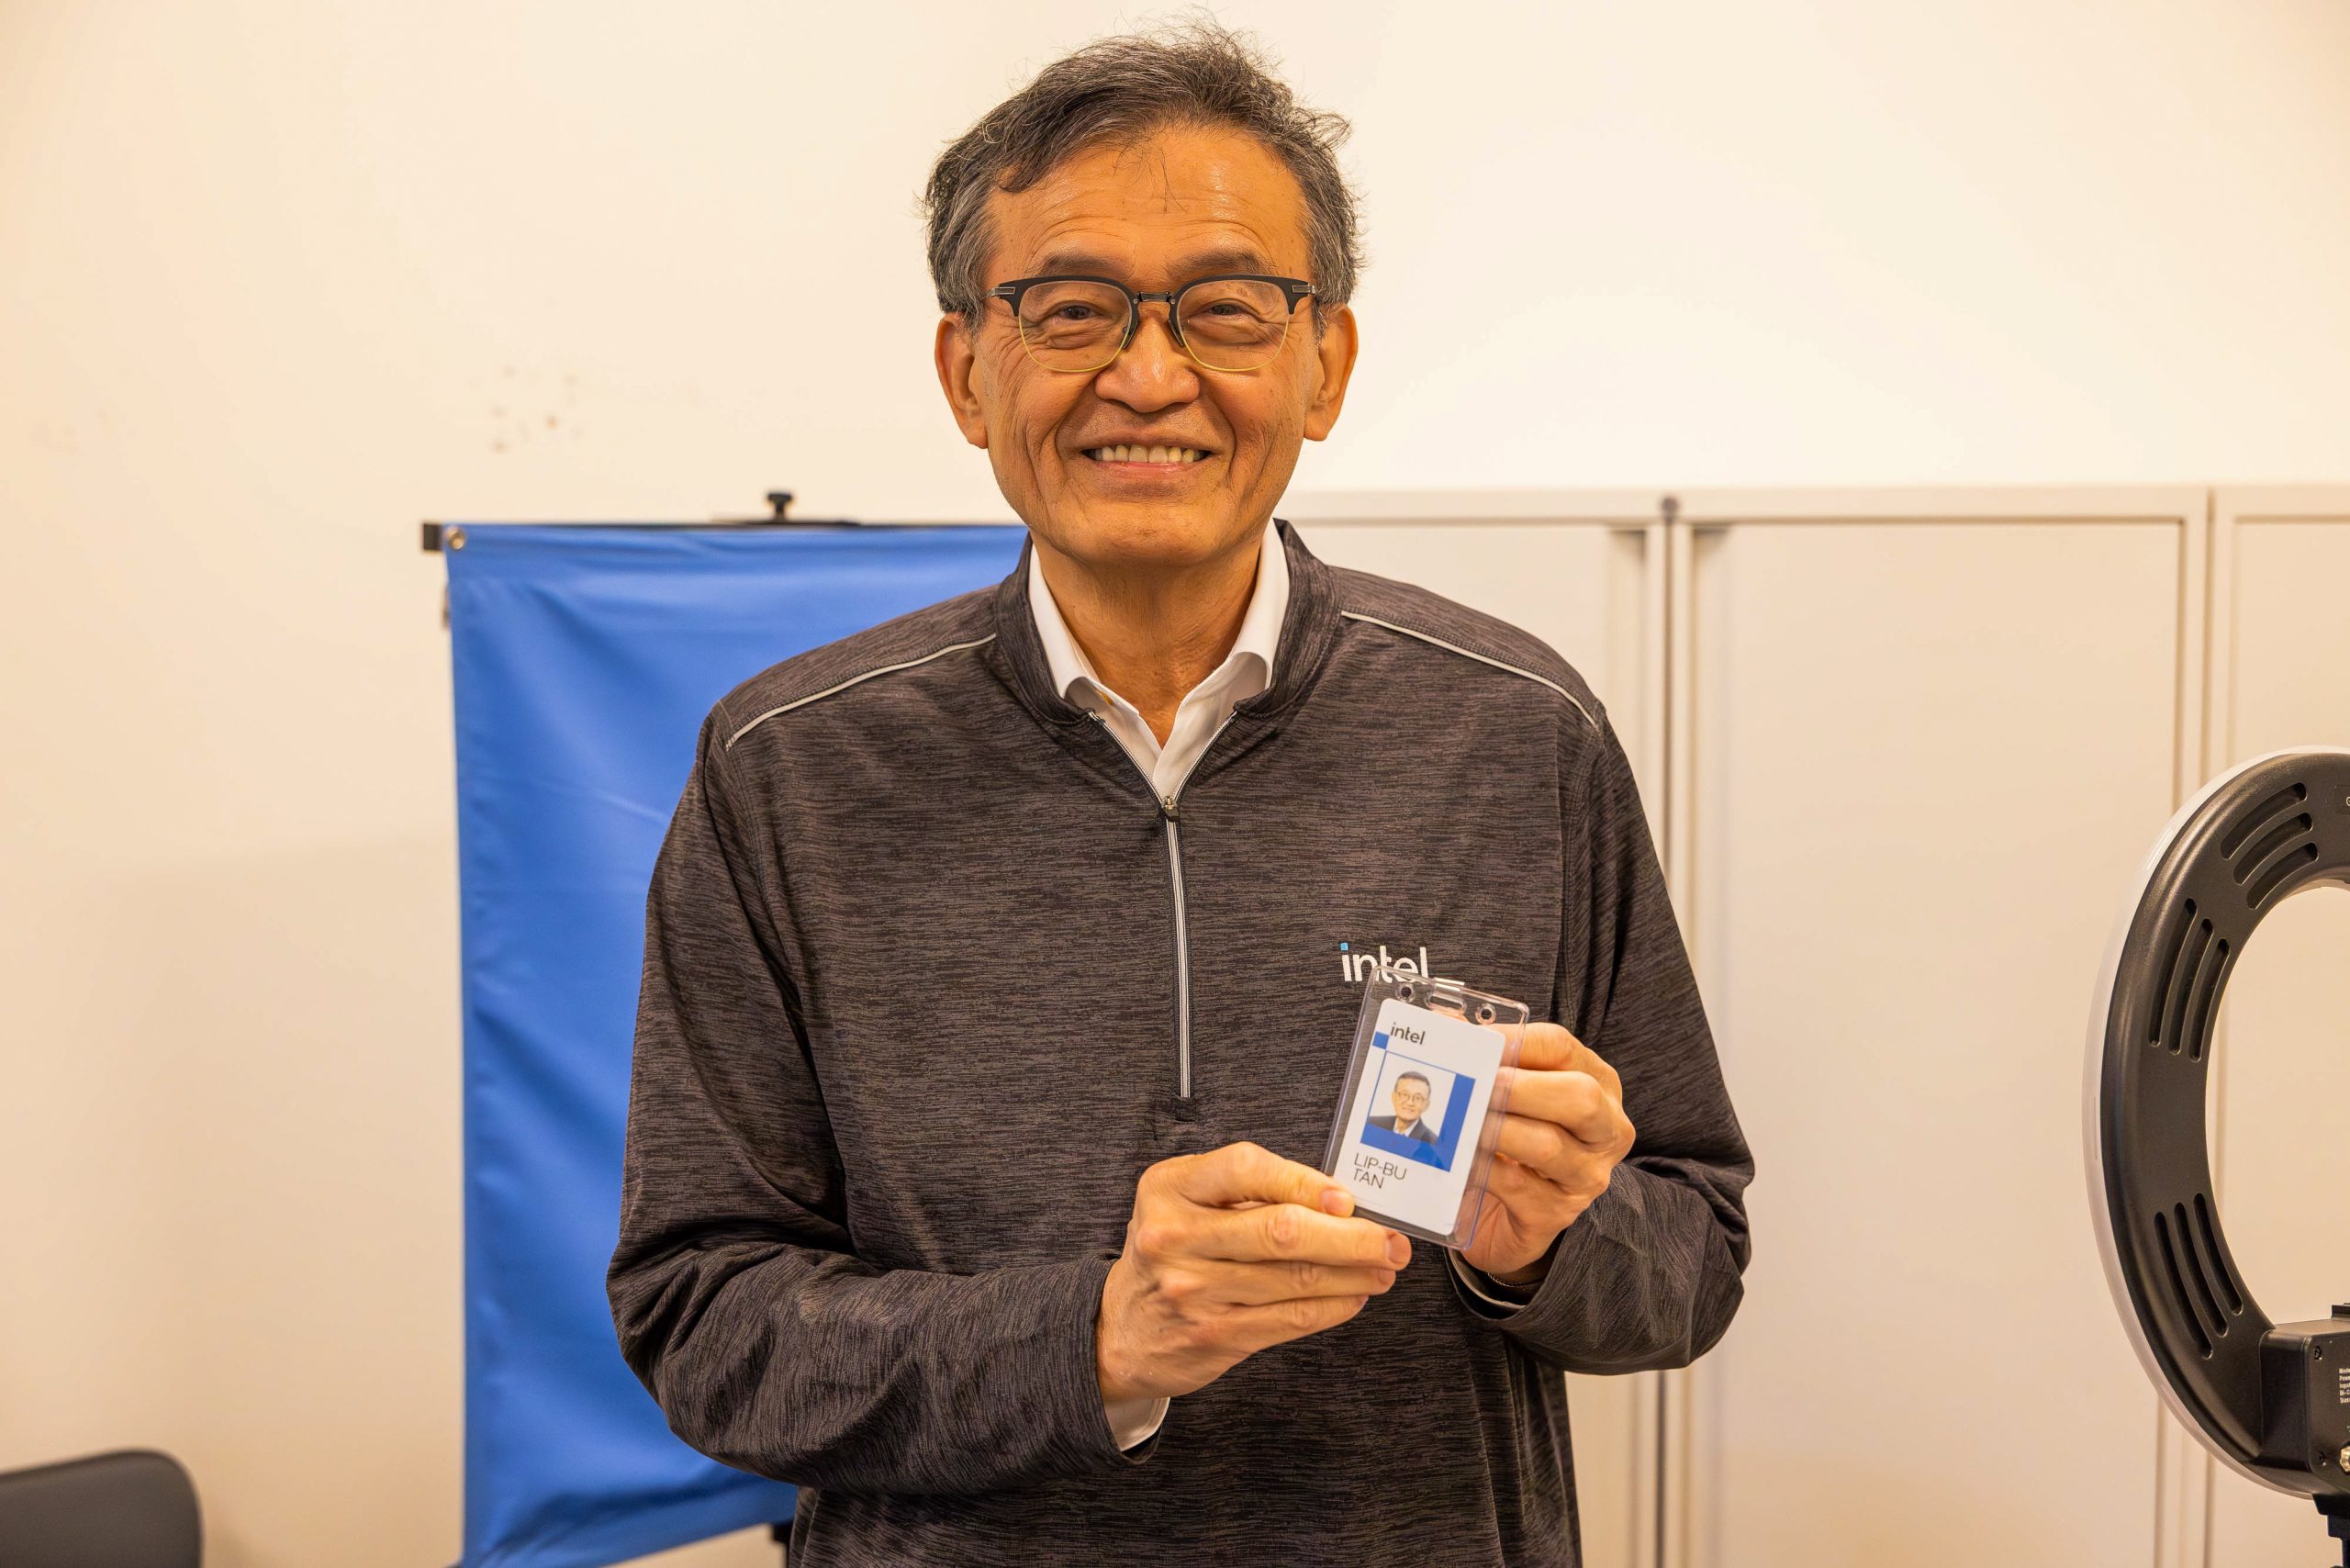
In recently shared remarks at a fireside chat held on October 24 by the Chinese-American Semiconductors Professionals Association, known as CASPA, Intel CEO Lip-Bu Tan described 18A as already in mass production and 14A as moving quickly toward formal PDK releases. He also said he had spoken with AMD Chair and CEO Lisa Su about possible areas of cooperation, without disclosing specific projects. For industrial decision makers, the value of this update is not the node names alone, but whether they translate into design readiness, supplier negotiation points and production risk controls.
This matters because semiconductor supply chains are no longer evaluated only by process labels. Buyers and engineering teams are asking whether a node can deliver usable design files, mature toolchains, predictable packaging yields and credible customer relationships. Intel's latest comments provide several concrete checkpoints.
18A and 14A: From Process Labels to Manufacturing Checkpoints
Since taking leadership of Intel, Lip-Bu Tan has placed intense focus on the company's two most important advanced logic nodes, 18A and 14A. The public update says 18A has entered mass production, while the next-generation 14A is progressing rapidly enough that its PDK sequence is already under discussion. A PDK is the package of design rules, models and technical files that a wafer foundry provides to chip-design companies so they can begin designing silicon for that manufacturing process.
Intel currently has a 0.5 version of the 14A PDK. The company plans to release a 0.9 version soon, followed by a 1.0 version in early next year to support formal mass production. That sequence gives outside observers a practical way to track readiness.
| 14A PDK milestone | What it signals | Why industrial buyers watch it |
|---|---|---|
| 0.5 version | Early test-stage design information | Useful for planning and early evaluation, not final production confidence |
| 0.9 version | Node has reached tape-out capability and risk-production readiness | Design teams can convert concepts into manufacturable chips under tighter rules |
| 1.0 version | Formal mass-production support version | Procurement and supply-chain teams can negotiate toward volume commitments |
The distinction between 0.9 and 1.0 is important. A 0.9 version is often read as evidence that tape-out is possible and risk production can begin. A 1.0 version moves the conversation closer to repeatable volume manufacturing. In other words, the roadmap is meaningful not because the names 18A and 14A are impressive, but because the PDK milestones reveal how much of the path is already engineered.
Customer Repair: 6 to 8 Months, 15 Issues and No More Lecturing
A second theme from the conversation was customer relationship repair, which can be as difficult as process engineering in foundry markets. Tan shared a case in which a customer waited 6 to 8 months for a meeting after he became Intel CEO. Once the discussion happened, the customer presented 15 problems that had existed with Intel in the past.
His description suggested that Intel's older operating style could sometimes involve lecturing customers rather than listening to them. Tan said he treated the 15 issues as a working list, responding item by item and resolving them, which eventually restored trust and led the customer to deepen its cooperation with Intel.
- Case lesson: Foundry selection is not only a technical decision; it is also a governance decision.
- Process lesson: A customer-facing issue list can convert a complaint relationship into a joint delivery program.
- Management lesson: Listening is not a soft skill in industrial supply chains; it affects qualification time and supplier reliability.
For managers reading through the lens of their own operations, the story is familiar. Advanced components and subsystems can fail not because no supplier exists, but because the interface between engineering, procurement and production is too slow to absorb customer-specific problems. A supplier that says it listens must show how it tracks issues, assigns owners and closes them within an auditable timeline.
AMD Cooperation: Strategic Signaling in a Competitor-Led Market
Tan confirmed that he had talked with Lisa Su, Chair and CEO of AMD, about areas where the two companies might explore cooperation in the future. He did not identify specific businesses, technologies or projects. The October 24 remarks did not provide implementation details, which means the statement should be treated as a strategic signal rather than a confirmed commercial arrangement.
Intel and AMD have been long-term rivals in the CPU market. If they were to cooperate in selected areas, it could change conversations across design, manufacturing and customer deployment. The practical effect, however, depends on the later disclosed scope of any partnership.
Channel Survey Data: Orders, Evaluations and One Unconfirmed Apple Story
A recent KeyBanc channel survey gives additional commercial context. According to that report, Intel has already received multiple foundry orders. These include network switch chips for Broadcom and server CPUs for Google. The survey also says Microsoft server processors and Nvidia gaming GPUs are reported to be expected for manufacturing by Intel.
The report also points to evaluation-stage interest from other large buyers. Amazon, Anthropic and SpaceX/Tesla Terafab are described as still assessing Intel's 18A-P and 14A process technologies. A notable trend is that many customers appear to prefer 14A over 18A-P at this stage, suggesting that design teams may be waiting for more mature PDK, packaging and yield evidence before committing volume.
The most high-profile claim concerns Apple. KeyBanc says Apple has reached a long-term, multi-generation foundry agreement covering production of M-series and A-series chips, with Intel's 14A process intended rather than the previously rumored 18A-P option. Neither Apple nor Intel has officially confirmed this report, and industry views remain divided. For procurement and competitive analysis, the correct treatment is therefore simple: classify it as a reported possibility, not a finalized supply-chain fact.
| Buyer or customer | Reported status | Node or product context |
|---|---|---|
| Broadcom | Reported foundry order | Network switch chips |
| Reported foundry order | Server CPUs | |
| Microsoft | Reported expectation | Server processors |
| Nvidia | Reported expectation | Gaming GPUs |
| Amazon, Anthropic, SpaceX/Tesla Terafab | Evaluating | 18A-P and 14A; many favor 14A |
| Apple | Reported long-term agreement, not confirmed | M-series and A-series chips, reportedly using 14A instead of 18A-P |
Advanced Packaging Yield: EMIB-T Substrate Bottlenecks
Another channel detail is especially relevant for industrial products that combine logic, memory and interconnect through advanced packaging. KeyBanc says the production yield for substrates used in Intel's EMIB-T advanced packaging technology is currently about 50% to 60%. The supplier Ibiden is described as performing better, while another supplier, UMTC, is reported to maintain yield around 20% to 30%.
These numbers matter because packaging substrate defects can undermine otherwise sound wafer processes. When a node moves from first silicon to volume production, bottlenecks often appear in adjacent steps such as substrate qualification, interposer alignment, thermal test, assembly scheduling and failure analysis. A yield band of 50% to 60% can still mean schedule variability; a yield band of 20% to 30% can mean that a buyer should treat the part as strategically constrained rather than commodity-ready.
Common Misconceptions Around Intel's 18A and 14A Update
- Misconception: A node name alone proves production maturity.
- Correction: The more useful evidence is the PDK sequence, mass-production status, customer evaluations and packaging yield, not the label 18A or 14A.
- Misconception: A 0.9 PDK means everything is locked for volume.
- Correction: A 0.9 version is generally read as support for tape-out and risk production; the 1.0 version in early next year is the more direct mass-production signal.
- Misconception: Intel and AMD cooperation automatically means CPU collaboration.
- Correction: Tan said only that possible cooperation areas were discussed; the specific scope was not disclosed.
- Misconception: A channel survey turns rumors into confirmed orders.
- Correction: Broadcom and Google were described as orders in the report; Apple's alleged long-term agreement remains unconfirmed and should not be treated as final sourcing information.
- Misconception: Advanced packaging is a secondary issue.
- Correction: Yield for EMIB-T substrates, including ranges of 50% to 60% and 20% to 30%, can directly shape cost, capacity and delivery reliability.
Action Recommendations for Manufacturing, Engineering and Supply Chain Teams
- Track PDK milestones, not headlines. If your products depend on Intel's advanced nodes, request the timing and scope of the 0.9 version and 1.0 version for 14A. Ask whether design-rule changes, model limitations or library updates will force revalidation.
- Treat tape-out and risk production as separate gates. A customer evaluation of 18A-P and 14A is not the same as a volume order. Build your supplier scorecard around tape-out capability, PDK version, yield history, packaging readiness and support responsiveness.
- Ask suppliers for an issue-resolution ledger. The customer case with 15 issues shows that trust is rebuilt through documented closure, not apologies. Require owners, dates, evidence and escalation paths for critical problems.
- Watch AMD cooperation only through announced scope. Until Intel and AMD specify concrete collaboration areas, use the talks as a market signal, not a procurement assumption.
- Model packaging as part of capacity. If a product uses advanced packaging, substrate yield variability can dominate delivery. Include supplier risk from Ibiden, UMTC or equivalent suppliers in cross-functional planning, even if your own design team does not control the substrate.
- Separate confirmed facts from reported expectations. For Apple, the key point is that a long-term multi-generation agreement covering M-series and A-series chips was reported but not confirmed. Procurement forecasts should remain scenario-based until official statements appear.
FAQ: What Industrial Buyers Should Take From the Intel Update
Q1. What did Lip-Bu Tan say about 18A?
A: Intel's CEO said 18A has entered mass production. For buyers, the next practical questions are which customers are shipping volume products, what PDK version they use and how packaging supply is performing.
Q2. What is the significance of 14A moving from 0.5 to 0.9 and then 1.0?
A: The 0.5 version is early testing. The 0.9 version suggests tape-out capability and risk-production progress. The planned 1.0 version in early next year is the more direct milestone for supporting formal mass production.
Q3. What does the possible cooperation with AMD mean?
A: Tan said he had discussed possible cooperation areas with Lisa Su, but did not specify them. The fact that Intel and AMD, long-term CPU competitors, are exploring cooperation is significant, but the operational impact depends on the later disclosed scope.
Q4. Are the Apple and Intel reports confirmed?
A: No. The KeyBanc report described an alleged long-term, multi-generation agreement covering M-series and A-series chips with 14A, but neither Apple nor Intel has officially confirmed it, and views differ in the industry.
Q5. Why should industrial managers care about advanced packaging yield?
A: Because final product delivery depends on more than logic die fabrication. If EMIB-T substrates show yield around 50% to 60% overall, or around 20% to 30% for one supplier, downstream assembly and project timing can remain constrained.
Q6. What is the main takeaway for WorldIndustrialWeekly readers?
A: Intel is trying to re-establish competitive position through 18A mass production, the 14A PDK path, customer issue resolution, reported large-account evaluations and advanced-packaging readiness. For industrial teams, the lesson is to convert process-node news into measurable checkpoints: PDK version, risk production, packaging yield, issue closure and confirmed orders.
When read together, the October 24 CASPA comments and the recent channel data describe a company moving from slogan-level manufacturing talk toward more concrete operational proof. 18A is no longer just a target; 14A is beginning to show the PDK path needed for tape-out and risk production. Intel's reported orders, customer evaluations and packaging-yield details also reveal where the risks remain: late-stage process maturity, substrate variability and unconfirmed long-term agreements. The AMD conversation, by contrast, is not yet a supply-chain change order, but it may become a strategic marker in the semiconductor industry's next configuration.